Have you ever found yourself dipping into your savings for a vacation, a car repair, or a medical bill—only to later panic when a real emergency hits?
That’s where understanding the difference between sinking funds and emergency funds becomes a game-changer for your financial life. They may sound similar, but they serve very different (and equally important) purposes.
In this post, let’s break it down simply so you can start using both wisely—whether you’re managing a household, saving for big goals, or trying to stay financially secure in India.
What is an Emergency Fund?
An emergency fund is your financial safety net. It’s meant for unexpected, urgent expenses like:
- Job loss
- Medical emergencies
- Car breakdowns
- Sudden travel for a family crisis
Think of it as your financial first-aid kit—it’s not for wants or planned events, but for true emergencies.
Key Features of an Emergency Fund:
- Should cover 3–6 months of essential expenses
- Kept in liquid, easily accessible accounts (like a savings account or liquid mutual fund)
- Not touched unless it’s a real emergency
What is a Sinking Fund?
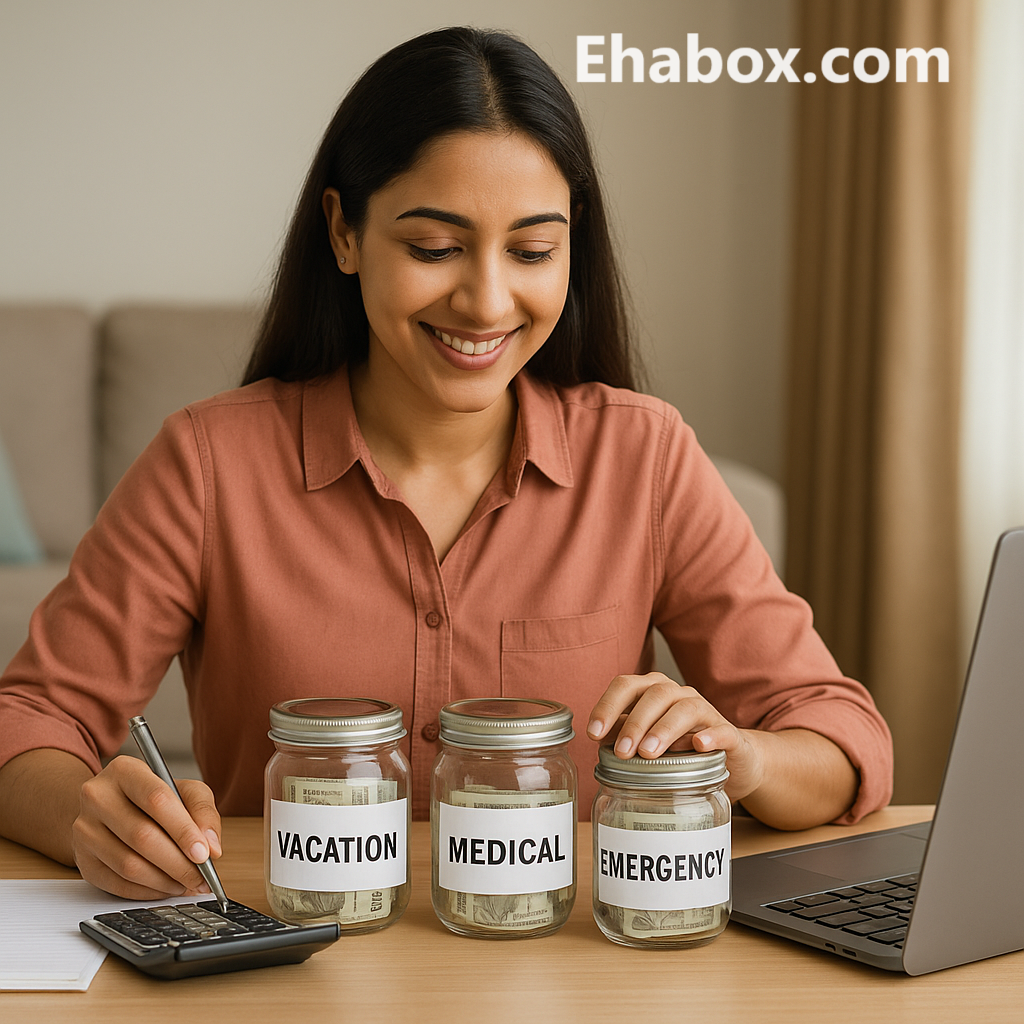
A sinking fund, on the other hand, is money you set aside intentionally for a known upcoming expense.
You’re planning ahead for things like:
- Annual insurance premiums
- Car maintenance
- Travel or vacation
- Home repairs
- Wedding or festival expenses
- Buying a phone/laptop
It helps you avoid using a credit card or your emergency fund when those predictable costs come up.
Key Features of a Sinking Fund:
- Meant for planned or semi-predictable expenses
- Built slowly over time (monthly contributions)
- Can be kept in a recurring deposit, savings account, or even an envelope system
Sinking Fund vs Emergency Fund: Side-by-Side Comparison
| Feature | Emergency Fund | Sinking Fund |
|---|---|---|
| Purpose | Unexpected expenses (emergencies) | Known, upcoming expenses |
| Usage | Only for true emergencies | Used as needed for planned goals |
| Access | Highly liquid (savings/liquid fund) | Moderate liquidity is fine |
| Amount Needed | 3–6 months of expenses | Depends on the upcoming goal |
| Emotional Impact | Reduces stress in crises | Prevents guilt when spending on planned items |
| Examples | Job loss, medical bill | Vacation, gadgets, insurance, car repair |
Why You Need Both
A common mistake is using an emergency fund for everything—even predictable costs. This drains your safety net and leaves you exposed.
By creating both types of funds, you:
- Stay financially prepared
- Avoid debt
- Build confidence in your money management
- Enjoy guilt-free spending when the time comes
How to Set Up Sinking Funds in India
Start simple. Think of 2–3 big upcoming expenses. For example:
Car Insurance (Due in 10 months)
Cost: ₹15,000 → Save ₹1,500/month
Diwali Shopping (In 6 months)
Budget: ₹12,000 → Save ₹2,000/month
You can:
- Use a dedicated savings account
- Label your UPI goals (like in Fi Money or Jupiter)
- Use a recurring deposit for set maturity
Pro Tip: Automate It!
Use apps or auto-debit to contribute monthly to your sinking funds. You’ll never feel the pinch, and the amount will grow silently in the background.
Final Thoughts: Sinking Fund and Emergency Fund = Financial Freedom Duo
Understanding the difference between sinking funds vs emergency funds can be the turning point in your personal finance journey.
- Emergency fund = peace of mind
- Sinking fund = guilt-free spending
Set them up. Name your goals. Watch your stress go down—and your confidence go up.